Canadian Natural (CNQ) U.S. Dividend Rises 2.3% to $0.452, 26-Year Streak
Canadian Natural Resources’ CNQ dividend rises to $0.452 a share for U.S. holders as record operating results and cash flow support the quarterly payout.
 CNQ — Canadian Natural Resources Limited
Key takeaways
- The U.S.-dollar quarterly dividend rose 2.3% to $0.452 per share from $0.442 because of currency translation.
- Canadian Natural says 2026 marks its 26th consecutive year of Canadian-dollar dividend increases, while the U.S.-dollar series has grown for 10 years.
- The dividend has a 43% earnings payout ratio and a SmarterDividends safety score of 74 with a C grade.
- CNQ’s 3.79% forward yield exceeds the Oil & Gas E&P industry median of 2.79%.
Canadian Natural Resources Limited’s quarterly dividend for U.S. holders rose 2.3% to $0.452 per share from $0.442. The shares traded ex-dividend on September 11, 2026. The change reflects currency conversion rather than a fresh increase in the company’s Canadian-dollar dividend, which the board maintained after raising it earlier in 2026.
Why the dividend changed
Canadian Natural declares its dividend in Canadian dollars, while holders of the New York-listed shares receive a U.S.-dollar equivalent. The board’s August 6 declaration maintained the Canadian-dollar rate established in March. The movement from $0.442 to $0.452 therefore reflects the exchange rate used for the U.S. payment, not another board-approved increase in the underlying rate.
That distinction matters because the company’s stated dividend policy and the U.S.-dollar payment series measure different things. Canadian Natural’s board determines the Canadian-dollar amount based on earnings, financial requirements and other conditions. Currency movements can raise or lower the amount received by U.S. shareholders even when the board leaves the declared rate unchanged.
The operating backdrop was supportive. Canadian Natural reported record quarterly adjusted net earnings and adjusted funds flow in the second quarter, along with record production. Higher output reflected strong oil-sands operations and additional interests acquired in earlier transactions. The company also completed another Peace River acquisition during the quarter and increased its annual production guidance while leaving planned operating capital spending unchanged, according to its second-quarter results.
Management linked the dividend’s durability to the company’s long-life, low-decline assets, balance sheet and cash generation. Chief Financial Officer Victor Darel said on the second-quarter earnings call that cash generation allowed Canadian Natural to combine shareholder distributions, share repurchases and debt reduction. The company’s allocation policy directs residual free cash flow between buybacks and debt repayment according to its net-debt position, after dividends and capital requirements.
Dividend track record
Canadian Natural says 2026 is its 26th consecutive year of dividend increases. That company record is based on the Canadian-dollar dividend declared by the board and is confirmed in the latest declaration. The comparable U.S.-dollar payment history shows 10 consecutive years of growth because foreign-exchange translation can interrupt the pattern seen by NYSE holders.
The recent U.S.-dollar payments illustrate that effect. The quarterly amount was $0.455 for the March 20, 2026 ex-dividend date, fell to $0.442 for June 23 and then rose to $0.452 for September 11. That sequence does not represent two board decisions to cut and then restore the dividend. It reflects a constant Canadian-dollar rate translated at different exchange rates.
Annual payments show a generally rising but uneven pattern. The total increased from $0.62 in 2020 to $0.78 in 2021, a 26.3% increase. It reached $1.75 across five payments in 2022, up 123.8%, before falling 22.1% to $1.37 in 2023. The company’s dividend history identifies an additional special dividend in 2022, explaining much of that rise and the subsequent decline. The total then increased 13.5% to $1.55 in 2024. The 2025 figure of $0.84 covers only two payments and is not a full-year comparison.
The last annual cut in the U.S.-dollar series occurred in 2015. Canadian Natural also completed a two-for-one share split in 2024, but the company restated earlier per-share dividend figures for the split, according to its annual information form. The split therefore does not explain the difference between the company’s 26-year Canadian-dollar record and the 10-year U.S.-dollar streak. Currency translation does.
Is the dividend covered?
The dividend consumes 43% of earnings. That payout ratio indicates earnings cover the distribution with room left for capital spending, debt reduction and repurchases, although earnings at an oil and gas producer remain sensitive to commodity prices, operating costs and production interruptions.
SmarterDividends assigns the dividend a safety score of 74 and rates it C. The C grade is a borderline assessment rather than a top-tier safety rating. It recognizes the moderate earnings payout while also reflecting the cyclicality of the business and the competing calls on cash, including a large capital program and balance-sheet targets.
Recent operating performance strengthens the near-term coverage picture without eliminating those risks. Second-quarter adjusted funds flow reached a company record, and net debt declined during the period. Canadian Natural’s filing also makes clear that dividends are deducted before the residual free cash flow used to determine repurchases and debt reduction, placing the regular distribution ahead of those discretionary allocations.
Yield and valuation
CNQ’s forward yield is 3.79%. That is above the 2.79% median for the Oil & Gas E&P industry but below the 4.23% median for the broader Energy sector. The comparison places CNQ above its immediate industry on income but below the sector benchmark, which includes higher-yielding energy businesses with different cash-flow and capital structures.
The shares trade at $48.52 after a 55.0% gain over one year. SmarterDividends estimates fair value at $35.04 and classifies the shares as overvalued, corresponding to 29% downside to that estimate. The valuation assessment is separate from dividend coverage: a payment can remain covered while the share price trades above an estimated fair value.
How Canadian Natural compares with peers
Canadian Natural’s 3.79% forward yield exceeds the 2.79% industry median and the yields of all four named peers. ConocoPhillips yields 2.62%, EOG Resources yields 2.88%, Occidental Petroleum yields 1.95%, and Devon Energy yields 2.66%.
The higher yield comes with a weaker safety grade. ConocoPhillips carries an A, while EOG, Occidental and Devon each carry a B. Canadian Natural’s grade is C. Earnings payout ratios provide additional context: CNQ’s 43% is close to ConocoPhillips’ 44%, but above EOG’s 31%, Occidental’s 30% and Devon’s 23%.
On the comparable U.S.-dollar growth series, Canadian Natural’s 10 consecutive years exceed ConocoPhillips’ 4, EOG’s 2, Occidental’s 4 and Devon’s 0. Canadian Natural’s company-reported Canadian-dollar record is longer at 26 years. The two measures should not be combined because exchange rates can alter the payments received by U.S. holders.
What to watch
Canadian Natural is scheduled to report third-quarter results on November 5, 2026, according to its investor calendar. The report will provide the next update on production, commodity-price realizations, operating costs, cash generation and net debt, all of which affect dividend coverage and the balance between debt reduction and repurchases.
Operational execution at Horizon is another concrete item. A planned turnaround began in September and was incorporated into annual production guidance. Investors can also monitor integration of the Peace River assets and the company’s progress toward its next net-debt threshold. Reaching that threshold would change the allocation of residual free cash flow toward repurchases, but it would not automatically change the regular dividend.
Management has put several medium- and long-term oil-sands growth projects on hold pending definitive agreements with Canadian governments. President Scott Stauth said shareholder returns would not be sacrificed if those projects proceed. The timing and capital requirements of any restart will be relevant because new projects would compete with debt reduction and shareholder returns for cash.
Payment details
The quarterly U.S.-dollar payment is $0.452 per share. September 11, 2026 was both the ex-dividend date for the U.S. shares and the record date identified in the company’s declaration. Investors generally had to purchase shares before the ex-dividend date to receive the payment.
The indicated annual dividend is $1.80 per share. At that rate, 100 shares generate $180.00 in annual dividend income before taxes and any future changes in the declared Canadian-dollar rate or the exchange rate applied to U.S. payments.
CNQ dividend data
From the SmarterDividends dataset, updated daily
- Forward yield
- 3.65%
- Payout ratio
- 43%
- Growth streak
- 10 yrs
- Safety grade
- C · 65/100
| Ex-dividend date | Amount | Change |
|---|---|---|
| Sep 11, 2026 | $0.4520 | +2.3% |
| Jun 23, 2026 | $0.4420 | -2.9% |
| Mar 20, 2026 | $0.4550 | +5.3% |
| Jun 13, 2025 | $0.4320 | +5.4% |
| Mar 21, 2025 | $0.4100 | +5.1% |
| Dec 13, 2024 | $0.3900 | +0.8% |
| Sep 13, 2024 | $0.3870 | +1.3% |
| Jun 17, 2024 | $0.3820 | -2.1% |
Frequently asked questions
How much is the CNQ dividend now?
Canadian Natural Resources’ quarterly dividend for U.S. holders is $0.452 per share, up 2.3% from $0.442.
How much does CNQ pay in dividends per year?
CNQ’s indicated annual dividend is $1.80 per share. That equals $180.00 in annual income for 100 shares before taxes or future changes.
When was CNQ’s latest ex-dividend date?
The latest CNQ ex-dividend date was September 11, 2026. Investors generally needed to own the shares before that date to qualify for the payment.
Is CNQ’s dividend safe?
The dividend has a 43% earnings payout ratio. SmarterDividends assigns it a safety score of 74 and a C grade, indicating borderline safety despite current earnings coverage.
How many years has CNQ increased its dividend?
Canadian Natural says 2026 is its 26th consecutive year of Canadian-dollar dividend increases. The U.S.-dollar payment series has grown for 10 consecutive years because currency translation can produce a different pattern.
What is CNQ’s dividend yield?
CNQ’s forward dividend yield is 3.79%, compared with a 2.79% Oil & Gas E&P industry median and a 4.23% Energy-sector median.
How does CNQ’s dividend compare with peers?
CNQ’s 3.79% yield is above ConocoPhillips at 2.62%, EOG Resources at 2.88%, Occidental Petroleum at 1.95% and Devon Energy at 2.66%. Its C safety grade is below the peers’ A or B grades.
Why did CNQ’s U.S. dividend increase?
The U.S.-dollar payment rose 2.3% to $0.452 because of currency conversion. Canadian Natural maintained its underlying Canadian-dollar quarterly rate after increasing it earlier in 2026.
Sources
See CNQ's full dividend profile
Yield, payout, safety score, history and the next ex-dividend date.
View CNQEvery dividend increases this month, with the data behind it: Dividend Increases, September 2026.
More dividend news
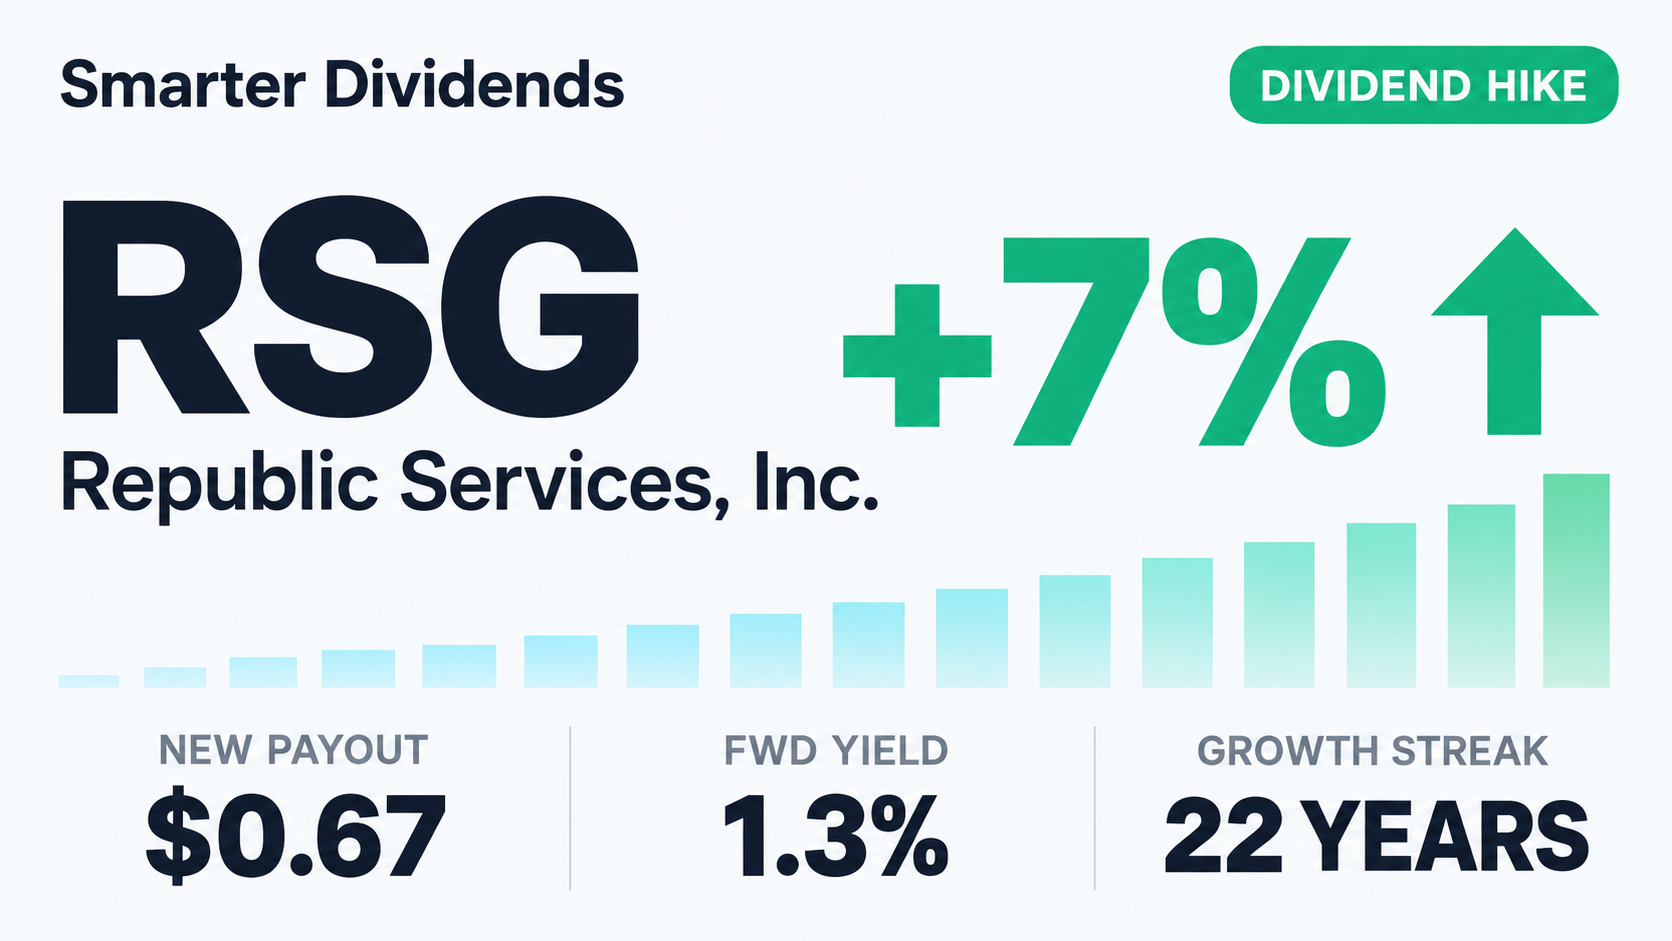
Republic Services Raises Quarterly Dividend 7.2% to $0.67
Republic Services raised its quarterly dividend 7.2% to $0.67, extending a 22-year growth streak as its stronger 2026 cash-flow outlook supports coverage.
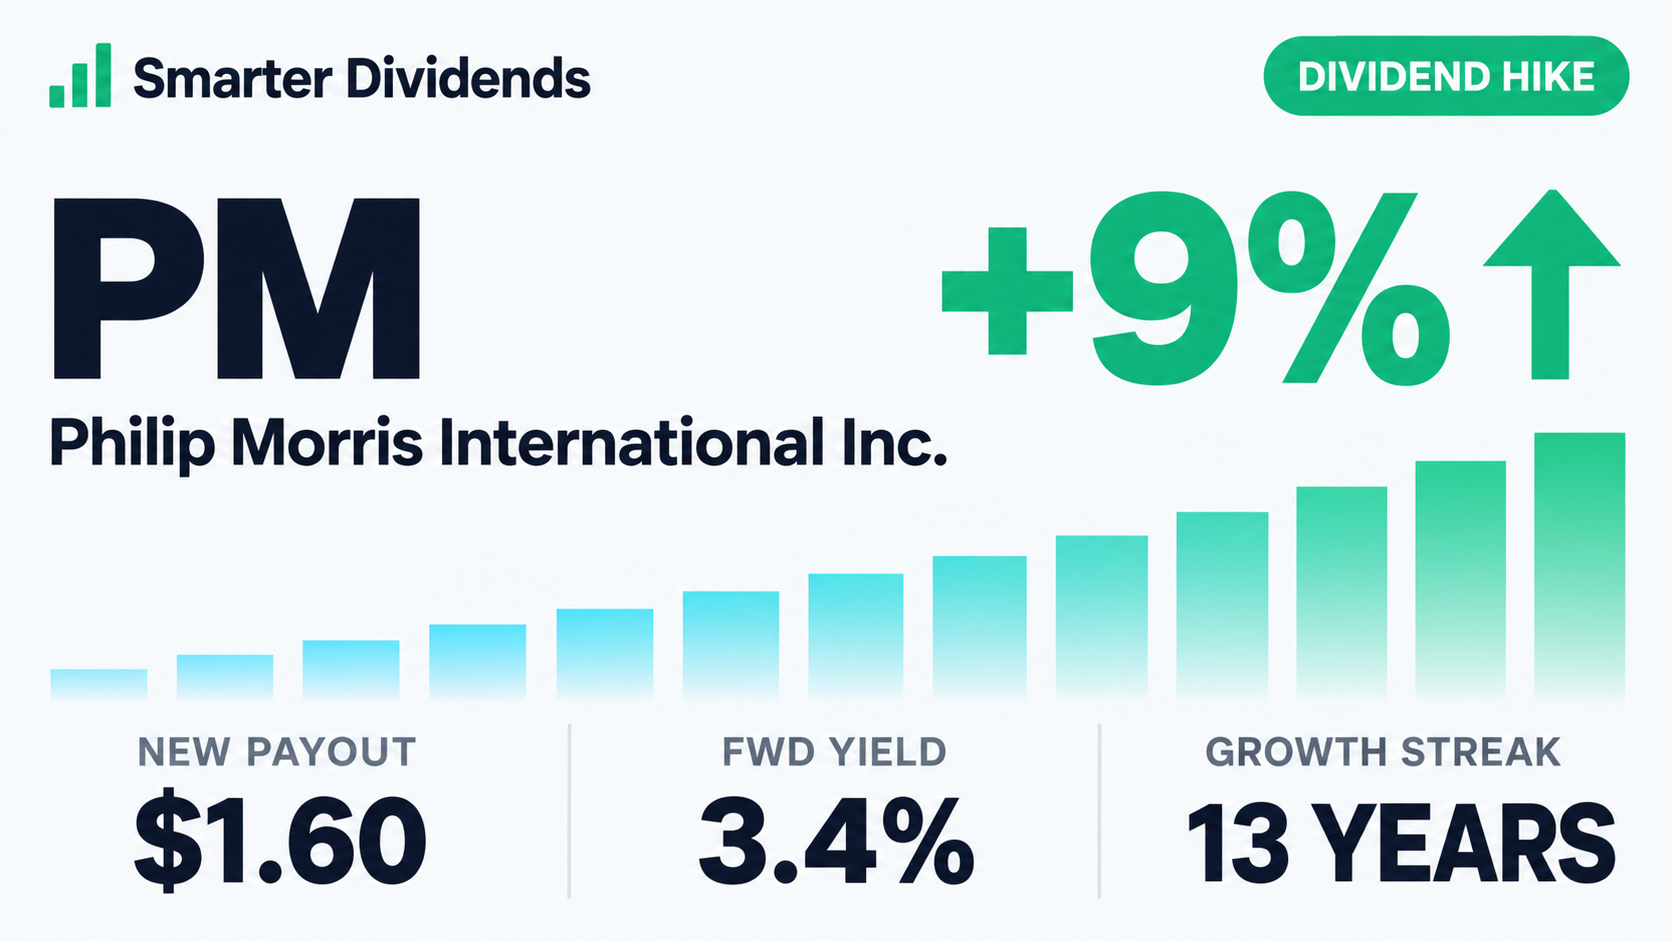
Philip Morris Raises Quarterly Dividend 8.8% to $1.60
Philip Morris lifted its quarterly payout 8.8% to $1.60, extending its annual growth record as earnings and cash-flow guidance support coverage.
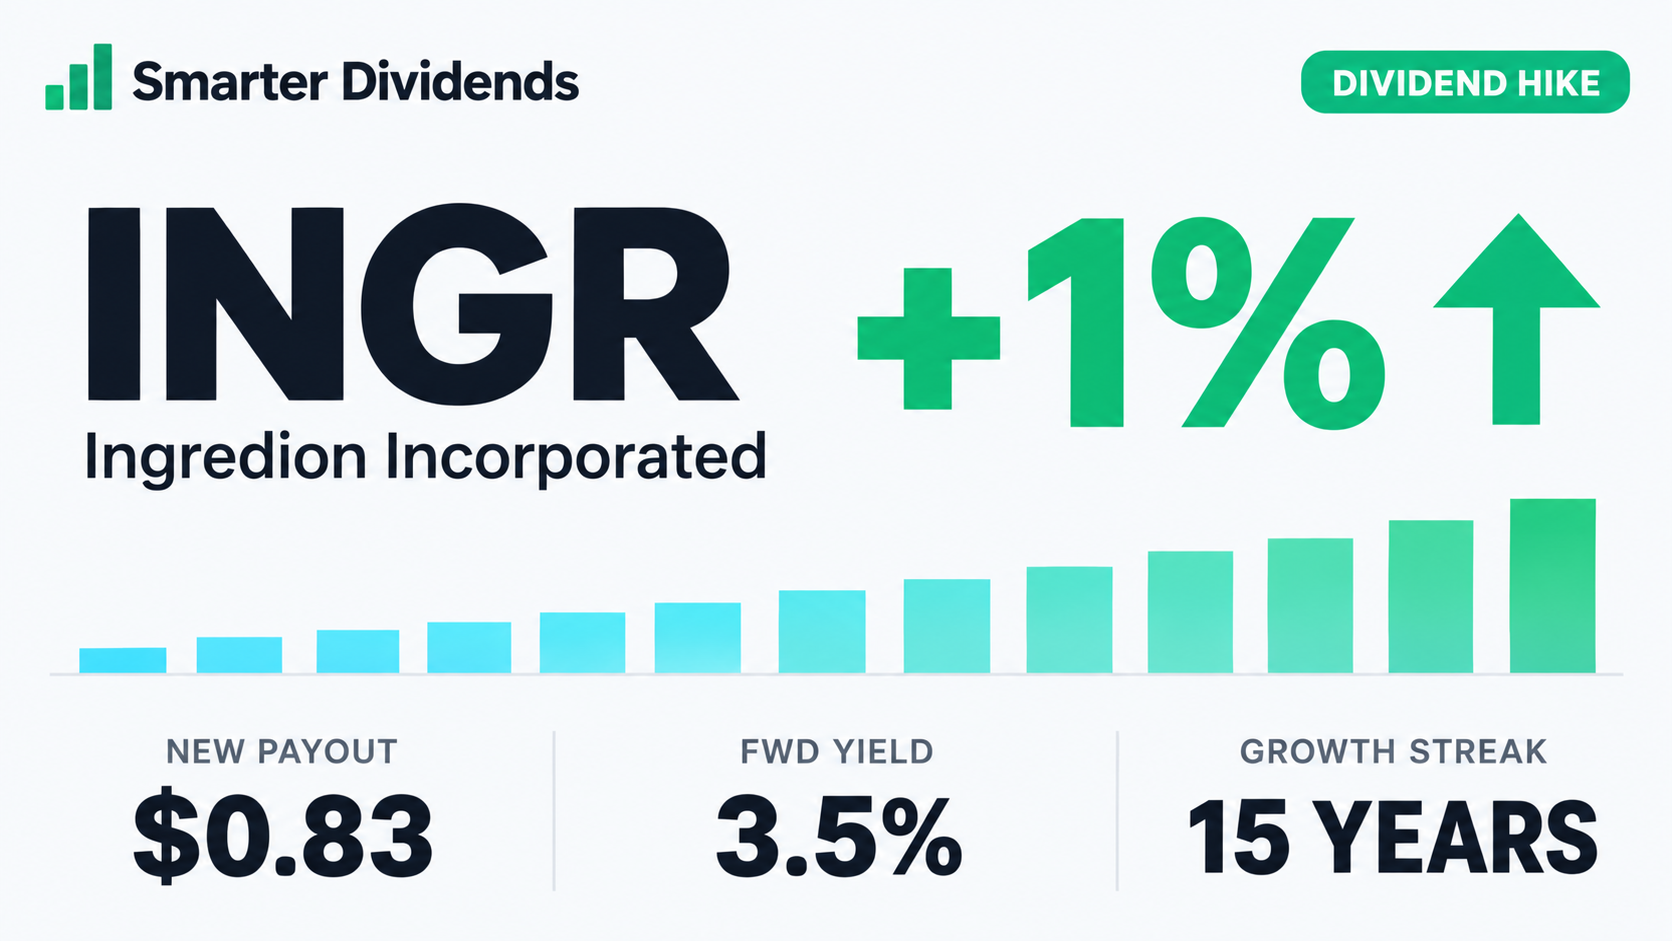
Ingredion Raises Quarterly Dividend 1.2% to $0.83
Ingredion lifted its quarterly dividend 1.2% to $0.83, extending a 15-year growth streak as earnings coverage remains strong despite operating pressures.
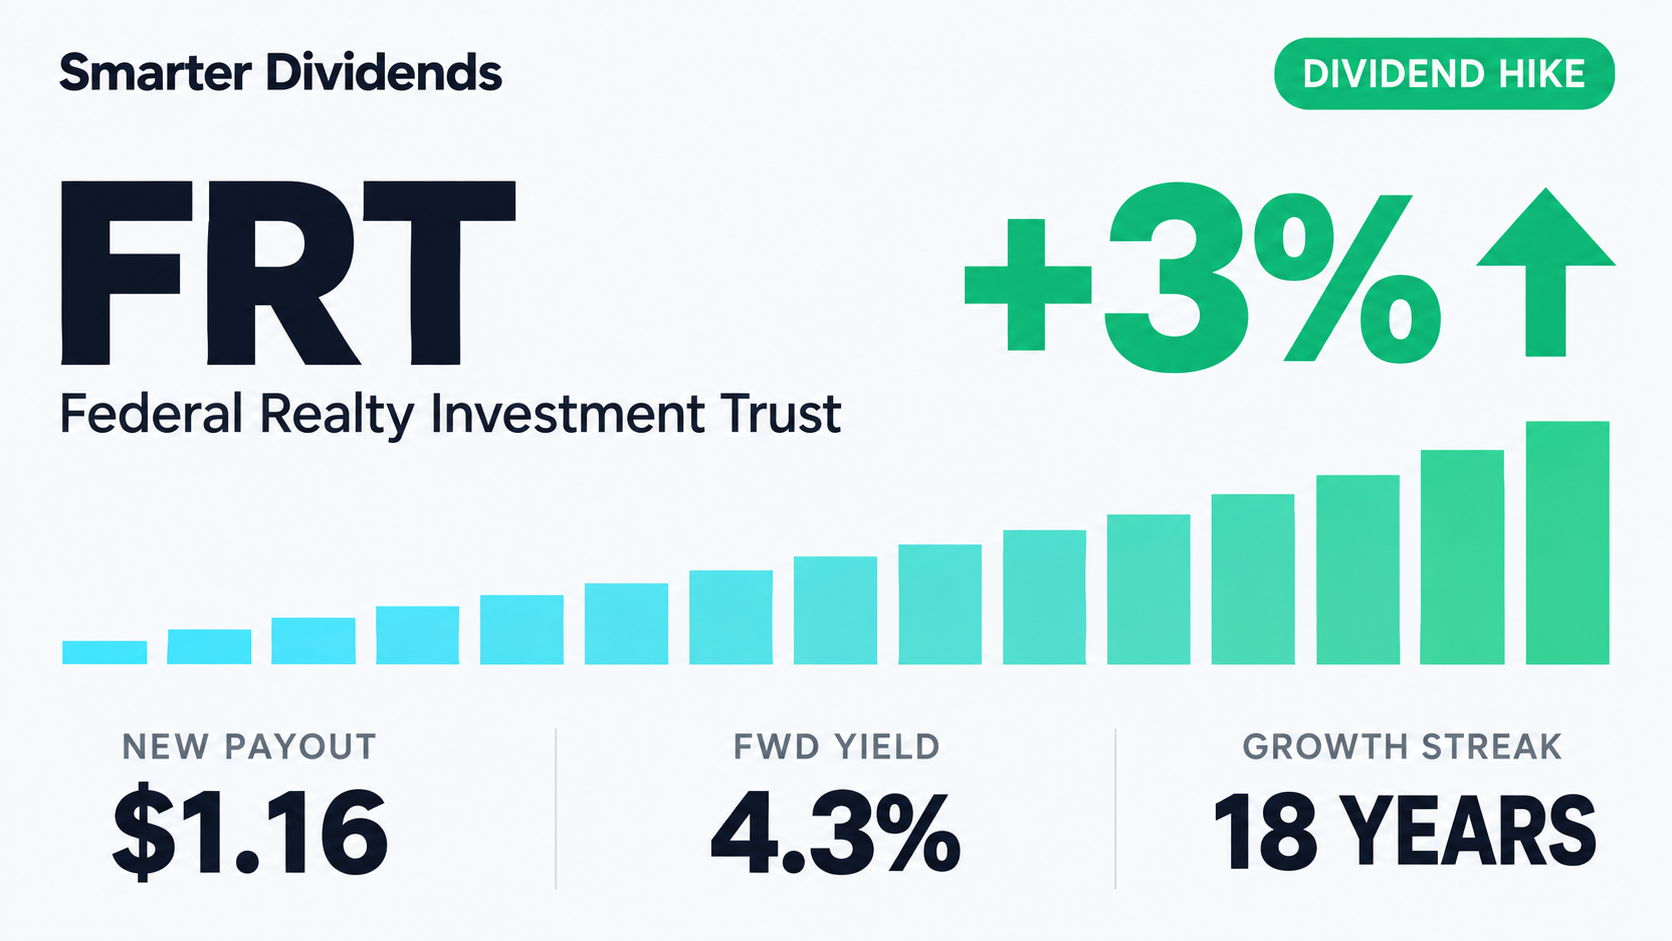
Federal Realty Raises Quarterly Dividend 2.7% to $1.16
Federal Realty lifted its quarterly dividend 2.7% to $1.16, backed by stronger core operations, raised guidance and a long record of increases.
Encompass Health Raises Quarterly Dividend 10.5% to $0.21
Encompass Health raised its quarterly dividend 10.5% to $0.21 as earnings coverage remained wide, though its 0.69% yield trailed healthcare.