Occidental Petroleum (OXY) Raises Dividend 7.7% to $0.28
Occidental Petroleum (OXY) raised its quarterly dividend to $0.28 a share, as debt reduction and cost savings strengthened its cash-flow capacity.
 OXY — Occidental Petroleum Corporation
Key takeaways
- Occidental raised its quarterly dividend 7.7% to $0.28 per share from $0.26.
- The new rate equals $1.12 annually, producing $112.00 in yearly income for every 100 shares.
- OXY’s 1.95% forward yield trails the 2.65% Oil & Gas E&P industry median and the 4.23% Energy sector median.
- The dividend has a 30% earnings payout ratio and a SmarterDividends safety score of 67, earning a B grade.
Occidental Petroleum Corporation raised its quarterly common dividend 7.7% to $0.28 a share from $0.26. The annual rate is now $1.12, and the shares traded ex-dividend on September 10, 2026. The increase continues a multiyear recovery in the payout after the company’s 2020 cut.
Why the dividend changed
Occidental linked the higher payout to a stronger balance sheet, lower interest expense and structural cost savings. Management said accelerated debt reduction had increased the company’s financial flexibility and helped support the board’s decision. Principal debt stood at $11.8 billion after the second quarter, while the resulting annualized interest expense was about $630 million lower than 2025 interest payments. The company continues to target a $10.0 billion principal-debt milestone. Occidental’s second-quarter earnings-call transcript
The dividend increase also followed a quarter of stronger cash generation and operating performance. Occidental reported $5.1 billion of operating cash flow from continuing operations and $3.0 billion of free cash flow before working capital, its highest quarterly amount since the third quarter of 2022. Global production averaged 1,433 thousand barrels of oil equivalent a day and exceeded the high end of guidance, with the Permian and Gulf of America businesses outperforming. Midstream and marketing results also exceeded guidance. Occidental’s second-quarter results
A major asset sale accelerated the balance-sheet repair. Occidental completed the sale of OxyChem on January 2, 2026, for an adjusted cash price of $9.5 billion. It used the after-tax proceeds and operating cash flow to repay about $8.6 billion of debt during the first half. This was not a dividend-related spin-off or special distribution. It was a portfolio transaction that reduced leverage and interest costs, expanding the capacity available for the regular dividend. Occidental’s second-quarter Form 10-Q
Management’s capital-allocation order remains conservative despite the increase. Debt reduction is the immediate cash-flow priority. After reaching the $10.0 billion milestone, Occidental plans to balance further principal reduction with cash accumulation ahead of a preferred-equity redemption in August 2029. Continuous share repurchases remain a lower priority until that redemption, according to management. Occidental’s second-quarter earnings-call transcript
Dividend track record
Occidental has increased its dividend for 4 consecutive years, but that record follows a severe reset. The company cut the dividend in 2020. Its full-year distributions totaled $0.82 that year and then fell 95.1% to $0.04 in 2021, reflecting the full-year effect of the reduced quarterly rate.
The recovery was initially rapid. Annual dividends rose 1,200.0% to $0.52 in 2022, increased 38.5% to $0.72 in 2023 and climbed 22.2% to $0.88 in 2024. The total advanced another 9.1% to $0.96 in 2025. The five-year annualized dividend growth rate is 88.8%, though that figure is heavily influenced by the unusually low post-cut starting point and does not describe a normal long-term growth rate.
The recent quarterly sequence shows a steadier pattern. The payment was $0.22 for the December 10, 2024 ex-dividend date, then $0.24 for each of the March, June, September and December 2025 dates. It increased to $0.26 for March 10 and June 10, 2026, before reaching $0.28 for September 10, 2026. That progression shows repeated increases, but the 2020 cut remains relevant evidence that Occidental will adjust the payout when commodity conditions and balance-sheet demands require it.
Is the dividend covered?
The dividend consumes 30% of earnings. That ratio indicates that most reported earnings remain available for debt reduction, investment and other corporate uses after the common dividend. It provides a meaningful earnings cushion at the current rate, although an exploration and production company’s earnings can change substantially with oil and gas prices.
SmarterDividends rates the dividend B, with a safety score of 67. That falls within the safe range of 66-79. The grade reflects solid current coverage rather than an absence of risk. Occidental’s own filing says commodity prices can affect capital-allocation decisions, while its recent dividend history demonstrates that the board has cut the distribution during periods of financial stress. Occidental’s second-quarter Form 10-Q
Yield and valuation
At a share price of $57.71, Occidental’s $1.12 annual dividend produces a 1.95% forward yield. That is below the Energy sector median of 4.23% and the Oil & Gas E&P industry median of 2.65%. The lower yield means the shares generate less current dividend income per dollar invested than those reference groups.
SmarterDividends estimates fair value at $66.74, representing 13% upside from the stated share price, and classifies the valuation as fair. The assessment places the shares within a reasonable valuation range rather than treating the dividend yield alone as evidence of overvaluation or undervaluation.
How Occidental compares with peers
Occidental’s 1.95% forward yield is below every listed peer and the 2.65% industry median. ConocoPhillips yields 2.62%, Canadian Natural Resources yields 3.79%, EOG Resources yields 2.88% and Devon Energy yields 2.66%. The comparison shows that Occidental’s dividend currently emphasizes a lower payout burden over a higher starting income rate.
The earnings payout ratios are closer. Occidental’s 30% compares with 44% for ConocoPhillips, 43% for Canadian Natural Resources, 31% for EOG Resources and 23% for Devon. Occidental therefore sits near EOG on earnings coverage, retains more earnings than ConocoPhillips and Canadian Natural Resources, and distributes more than Devon.
Dividend records and safety grades provide a separate distinction. Occidental and ConocoPhillips each have 4 consecutive years of growth, while Canadian Natural Resources has 10, EOG has 2 and Devon has 0. SmarterDividends assigns Occidental and EOG a B, ConocoPhillips an A, Canadian Natural Resources a C and Devon a B. These measures compare current income, coverage and consistency; they do not rank the companies as investments.
What to watch
The first marker is continued progress toward the $10.0 billion principal-debt milestone. Management has tied the dividend decision to falling interest costs and structural savings, so future quarterly disclosures on debt, unrestricted cash and interest expense will show whether that support continues. Investors can also track the balance between further debt reduction, cash reserved for the August 2029 preferred-equity redemption and opportunistic repurchases. Occidental’s second-quarter earnings-call transcript
Operational execution is the second marker. Occidental guided to third-quarter production of 1.4 million to 1.44 million barrels of oil equivalent a day, raised its full-year production guidance and maintained full-year capital guidance of $5.5 billion to $5.9 billion. It also expects to begin full commissioning of the STRATOS direct-air-capture plant around year-end as that project moves toward operations. Results against those plans will affect cash generation and capital needs, while the company continues to identify commodity-price volatility as a material influence on its financial results. Occidental’s second-quarter earnings-call transcript Occidental’s Form 10-Q
Payment details
The quarterly dividend is $0.28 per share, up from $0.26. The shares traded ex-dividend on September 10, 2026. To qualify for that distribution, shares had to be purchased before the ex-dividend date.
The new quarterly rate equates to an annual dividend of $1.12 per share. At that rate, 100 shares produce $112.00 in annual dividend income before taxes, assuming the rate remains unchanged and all four quarterly payments are made.
OXY dividend data
From the SmarterDividends dataset, updated daily
- Forward yield
- 1.80%
- Payout ratio
- 28%
- Growth streak
- 4 yrs
- Safety grade
- B · 69/100
| Ex-dividend date | Amount | Change |
|---|---|---|
| Sep 10, 2026 | $0.2800 | special |
| Jun 10, 2026 | $0.2600 | special |
| Mar 10, 2026 | $0.2600 | special |
| Dec 10, 2025 | $0.2400 | special |
| Sep 10, 2025 | $0.2400 | special |
| Jun 10, 2025 | $0.2400 | special |
| Mar 10, 2025 | $0.2400 | special |
| Dec 10, 2024 | $0.2200 | special |
Frequently asked questions
How much is OXY’s dividend now?
OXY’s quarterly dividend is $0.28 per share, up 7.7% from $0.26.
How much does OXY pay in dividends per year?
The annual dividend is $1.12 per share. At that rate, 100 shares generate $112.00 in annual dividend income before taxes.
What was OXY’s September 2026 ex-dividend date?
The shares traded ex-dividend on September 10, 2026. Investors had to purchase shares before that date to qualify for the associated payment.
Is OXY’s dividend safe?
SmarterDividends gives OXY a B safety grade and a score of 67, within the safe range of 66-79. The 30% earnings payout ratio indicates current coverage, although commodity-price exposure and the 2020 cut remain relevant risks.
How many consecutive years has OXY increased its dividend?
Occidental has increased its dividend for 4 consecutive years. The current streak began after the company cut its payout in 2020.
What is OXY’s dividend yield?
OXY’s forward dividend yield is 1.95% at a share price of $57.71.
How does OXY’s dividend compare with its peers?
OXY’s 1.95% yield is below the 2.65% industry median and the listed peer yields of 2.62% to 3.79%. Its 30% earnings payout ratio is below ConocoPhillips’ 44% and Canadian Natural Resources’ 43%, near EOG Resources’ 31%, and above Devon Energy’s 23%.
Why did Occidental raise its dividend?
Management tied the increase to debt reduction, lower interest expense, cost efficiencies and stronger financial flexibility. Second-quarter free cash flow before working capital reached $3.0 billion, while principal debt fell to $11.8 billion, according to [Occidental](https://www.oxy.com/news/news-releases/occidental-announces-2nd-quarter-2026-results/).
Sources
See OXY's full dividend profile
Yield, payout, safety score, history and the next ex-dividend date.
View OXYEvery dividend increases this month, with the data behind it: Dividend Increases, September 2026.
More dividend news
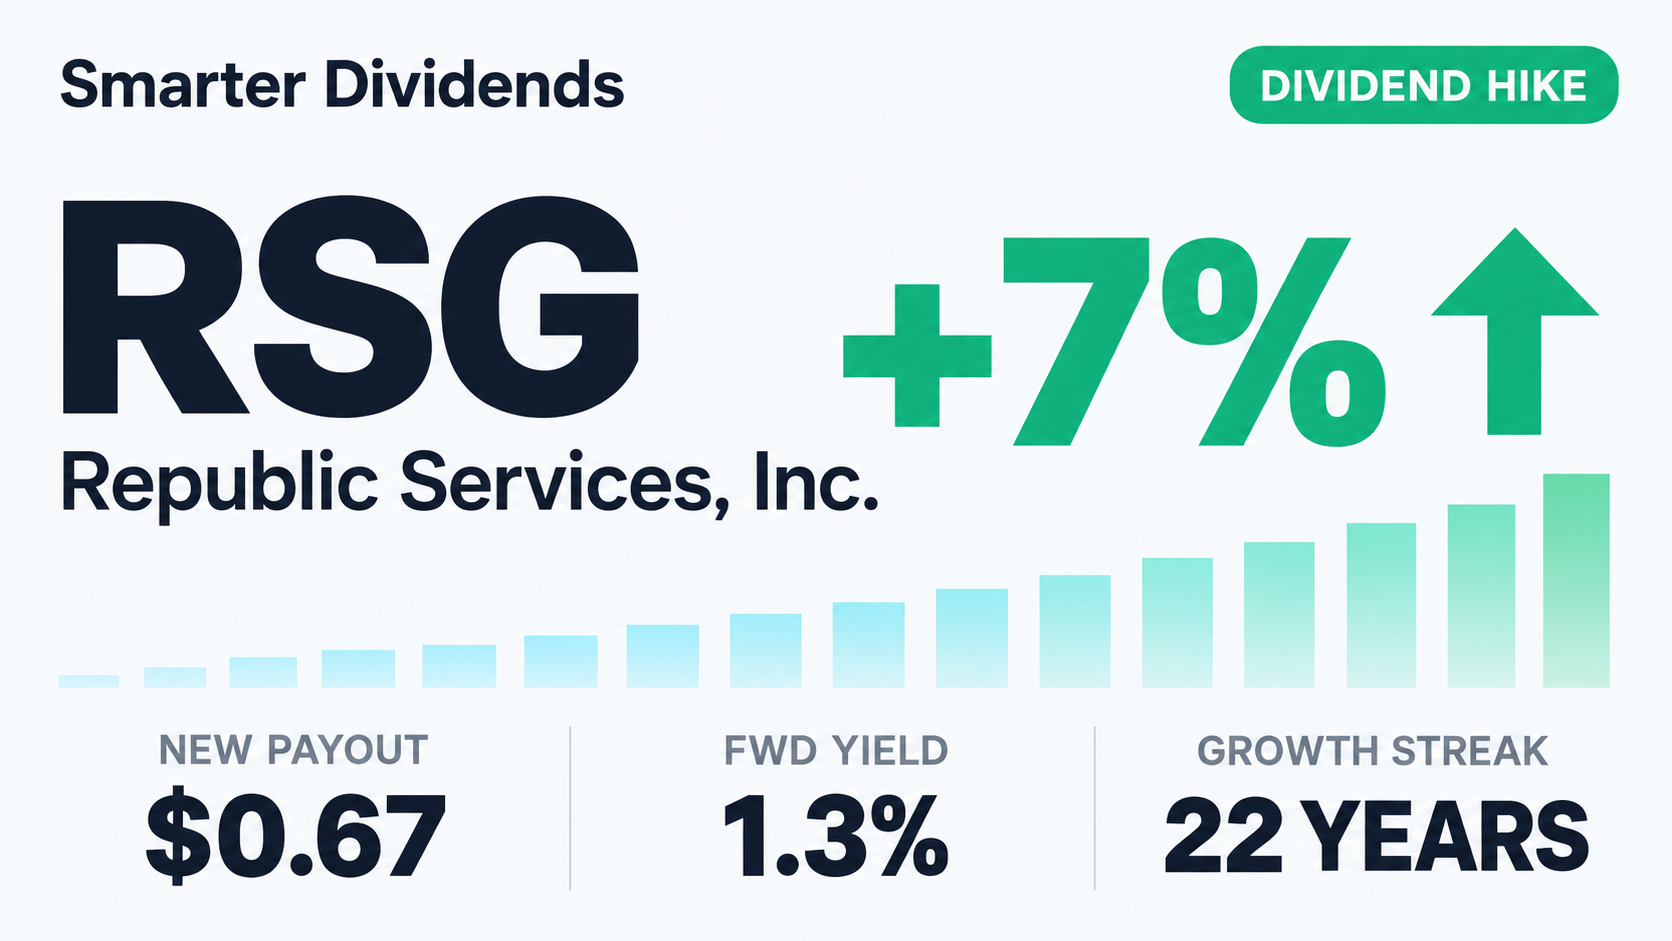
Republic Services Raises Quarterly Dividend 7.2% to $0.67
Republic Services raised its quarterly dividend 7.2% to $0.67, extending a 22-year growth streak as its stronger 2026 cash-flow outlook supports coverage.
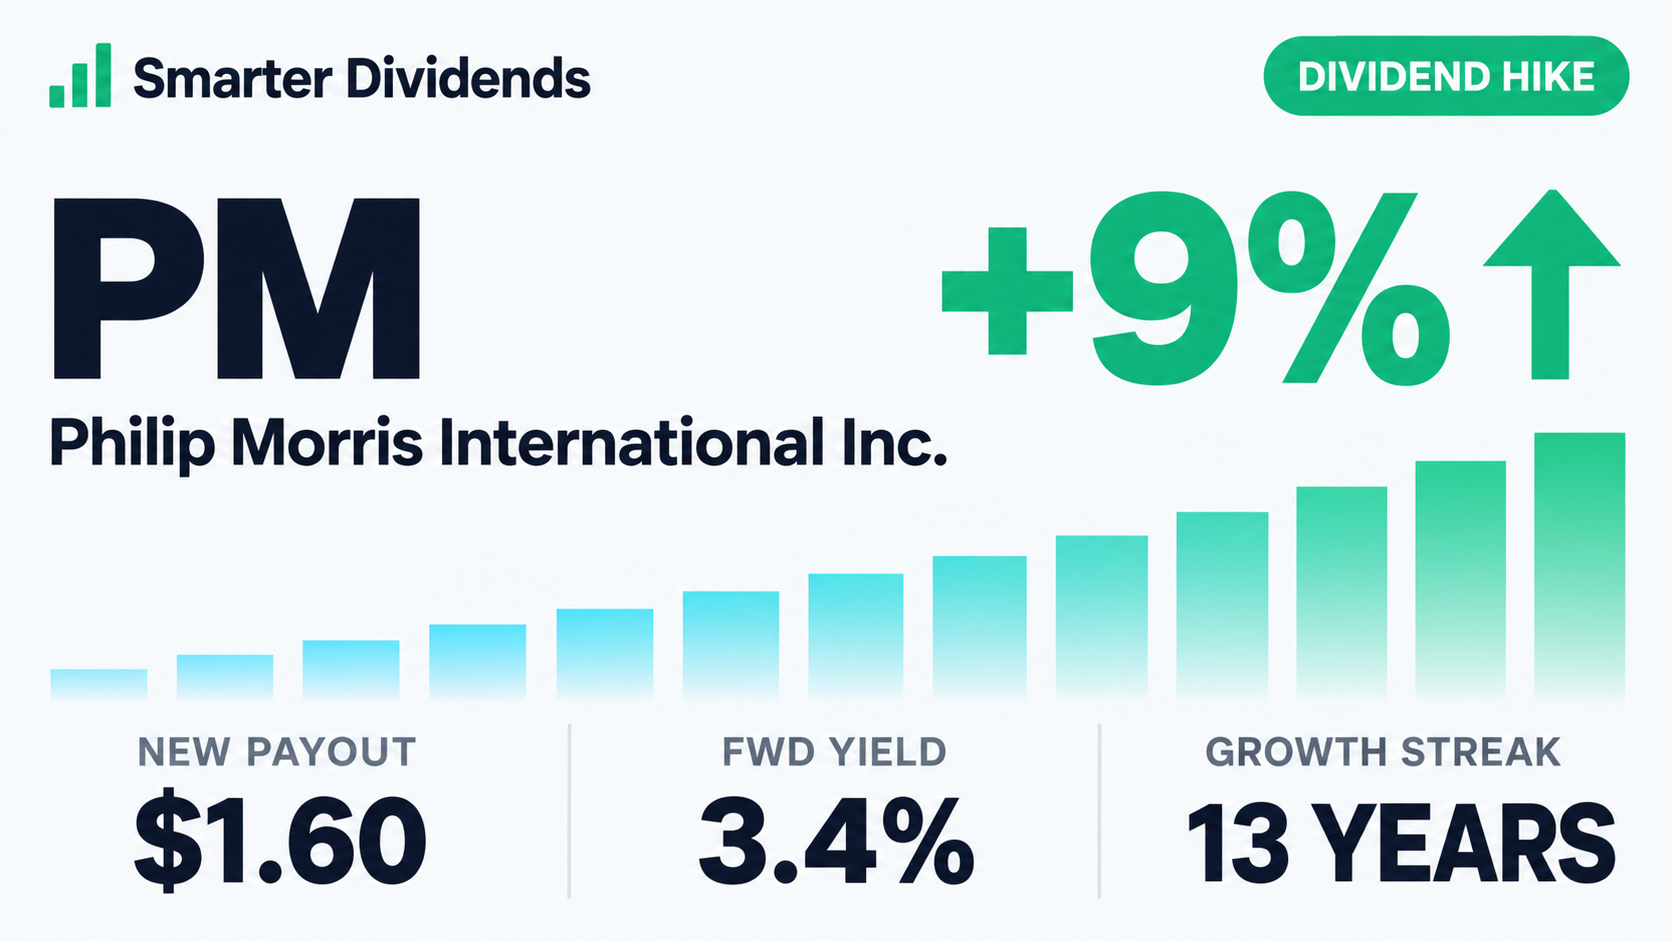
Philip Morris Raises Quarterly Dividend 8.8% to $1.60
Philip Morris lifted its quarterly payout 8.8% to $1.60, extending its annual growth record as earnings and cash-flow guidance support coverage.
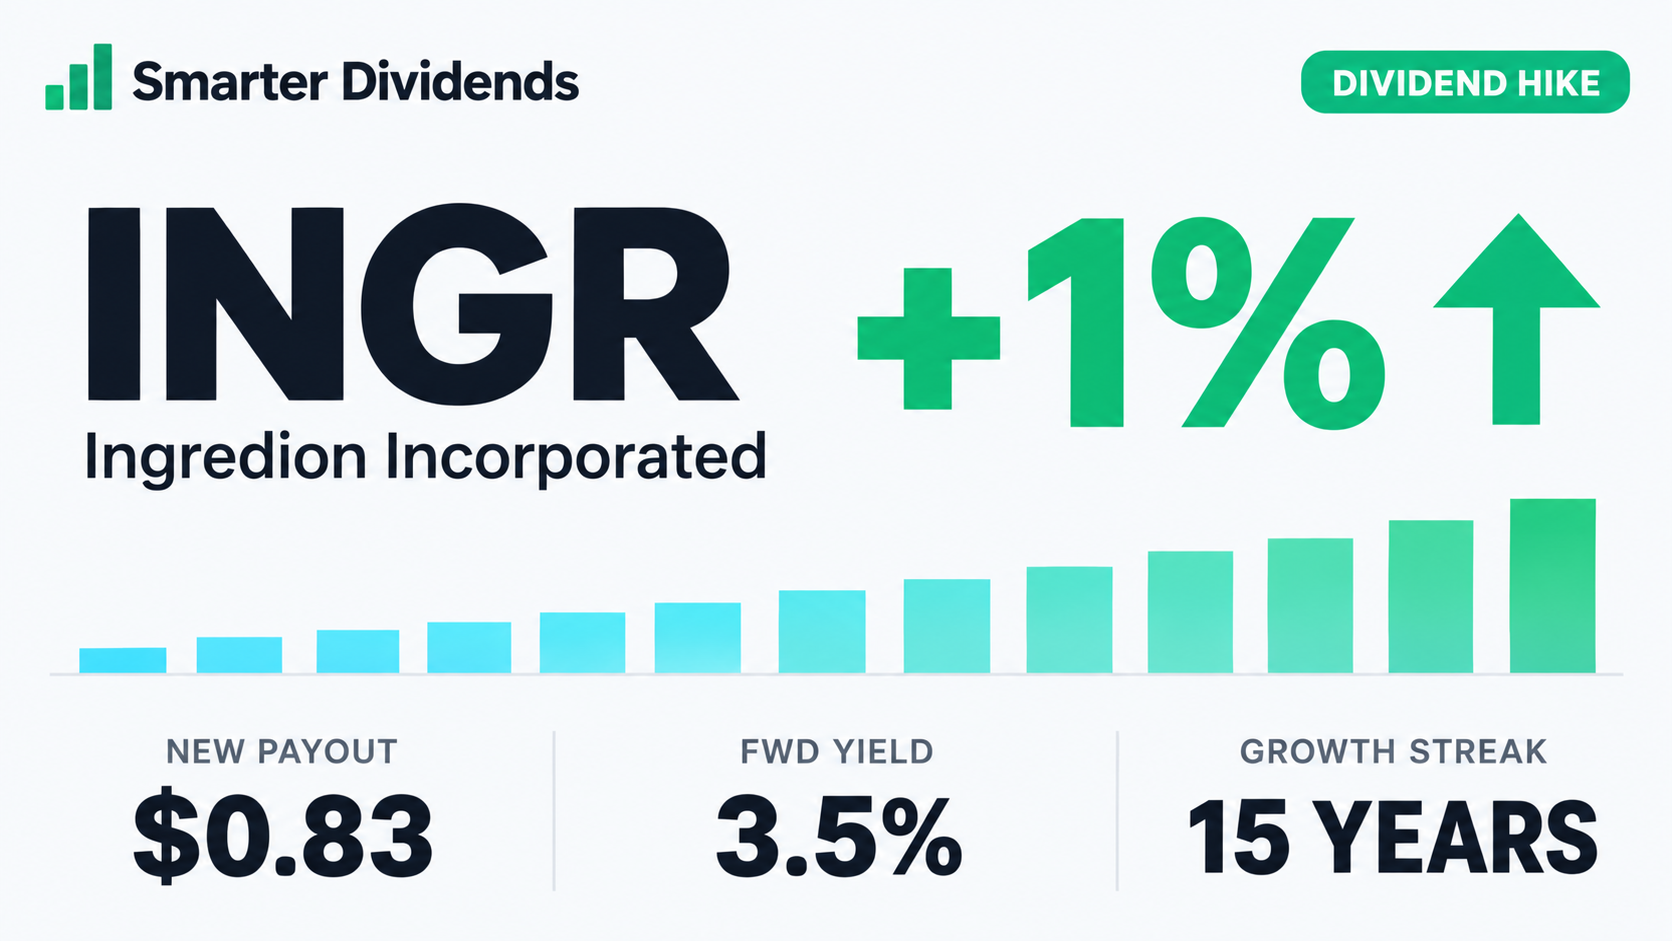
Ingredion Raises Quarterly Dividend 1.2% to $0.83
Ingredion lifted its quarterly dividend 1.2% to $0.83, extending a 15-year growth streak as earnings coverage remains strong despite operating pressures.
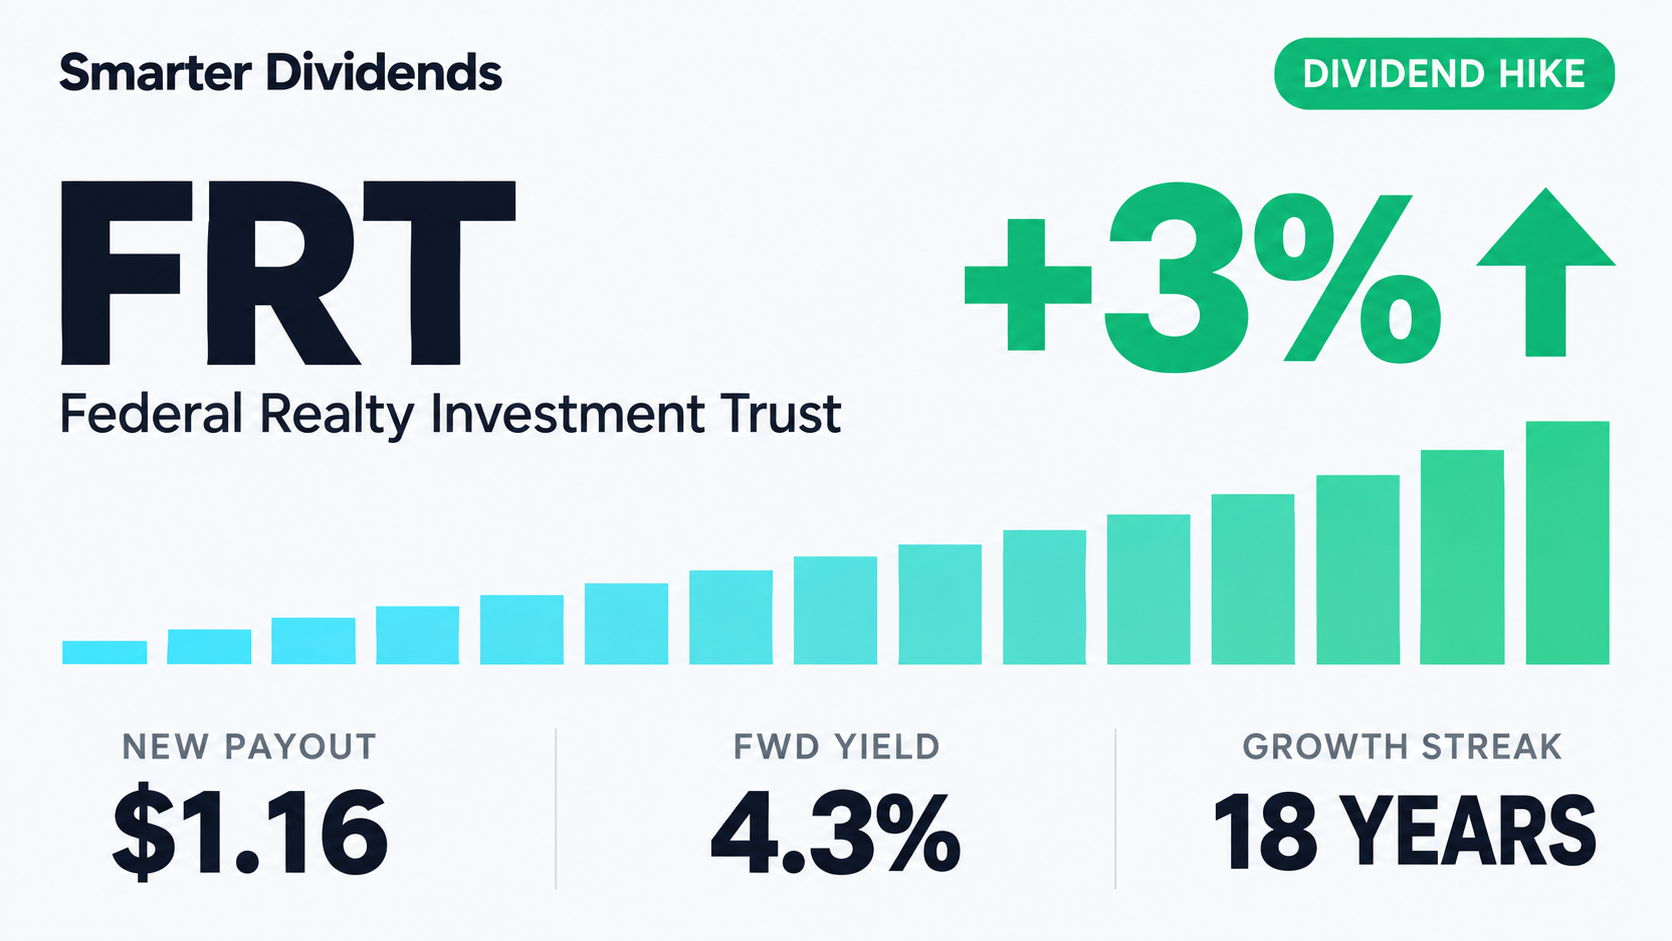
Federal Realty Raises Quarterly Dividend 2.7% to $1.16
Federal Realty lifted its quarterly dividend 2.7% to $1.16, backed by stronger core operations, raised guidance and a long record of increases.
Encompass Health Raises Quarterly Dividend 10.5% to $0.21
Encompass Health raised its quarterly dividend 10.5% to $0.21 as earnings coverage remained wide, though its 0.69% yield trailed healthcare.