Tennant Company Raises Dividend 4.8%, Extends 55-Year Streak
Tennant lifts its quarterly payout to $0.325, extending a 55-year record as cash conversion remains pressured by working-capital and ERP issues.
 TNC — Tennant Company
Key takeaways
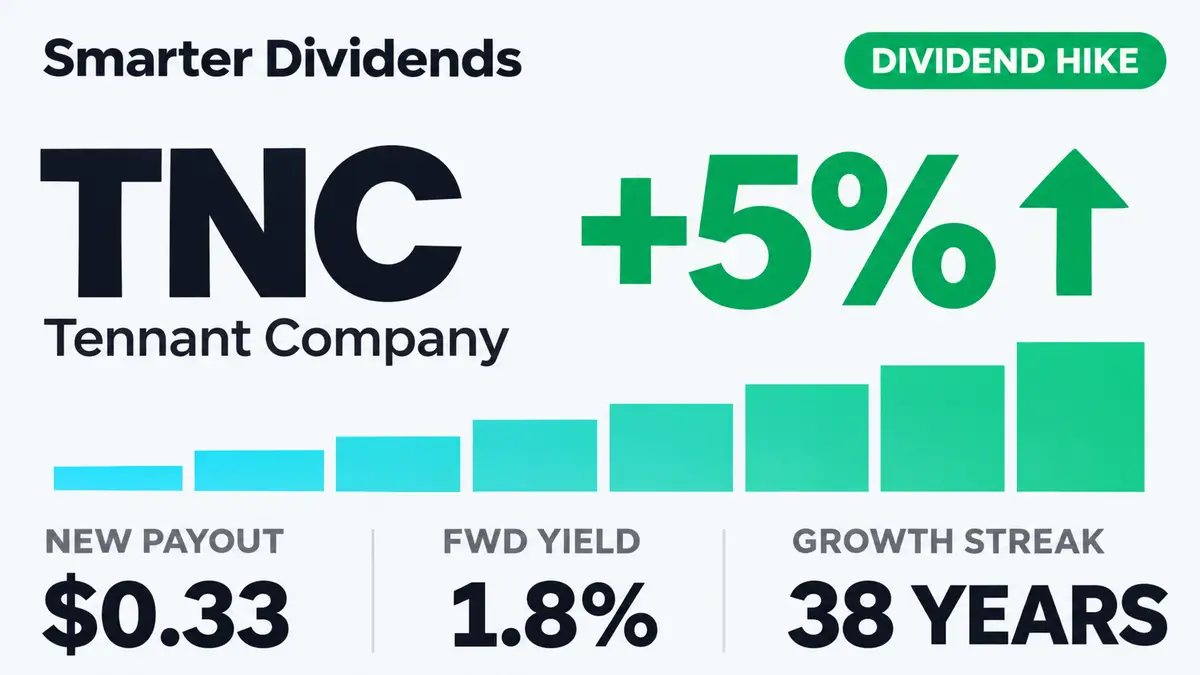
- The quarterly dividend rose 4.8% to $0.325 per share.
- The new annual dividend is $1.30 per share, equal to $130.00 for every 100 shares.
- The dividend has a 91% earnings payout ratio and an A safety grade with a score of 86.
- The 1.80% forward yield is above the Industrials sector median of 1.60%.
Tennant Company raised its quarterly dividend 4.8% to $0.325 per share from $0.31. The shares trade ex-dividend on November 30, 2026, and the payment is due December 15, 2026. The new rate equals an annual dividend of $1.30 per share and annual income of $130.00 for every 100 shares.
Why the dividend changed
Tennant’s announcement offered no specific financial trigger for the increase. It said the board authorized the higher payment and identified the action as the company’s 55th consecutive annual dividend increase. The release did not connect the decision to a stock split, merger, spin-off or special distribution. Tennant’s dividend announcement therefore points to continuity in its capital-return policy rather than a change in corporate structure.
The increase came alongside an improvement in third-quarter earnings but continued pressure on cash conversion. Tennant reported third-quarter net sales of $322.3 million, compared with $303.3 million a year earlier, while net income increased to $19.5 million from $14.9 million. The quarter’s gross margin was 42.3%, down 40 basis points, and included a $6.1 million tariff-refund benefit. Excluding that benefit, management attributed the underlying margin pressure mainly to inflation, parts availability and production inefficiencies. Tennant’s quarterly-results materials and its quarterly SEC filing provide the operating context.
Cash flow was the weaker part of the quarter’s financial picture. Tennant used $14.3 million of operating cash during the first nine months, compared with $50.8 million generated in the prior-year period. Management attributed the reversal to lower operating performance and increased working-capital requirements, including higher receivables and inventories and lower accounts payable. It said North American enterprise-resource-planning problems continued to affect working capital and cash conversion.
Management characterized 2026 as an operational transition year focused on improving execution, optimizing the North American ERP platform and capturing productivity and cost efficiencies. It also said spending, liquidity, working capital and capital allocation remained subject to disciplined management. The higher dividend indicates that the board maintained its long-term distribution policy despite those near-term operating constraints. It does not remove the importance of restoring cash generation.
Dividend track record
The payment history shows a regular pattern of one annual increase followed by four equal quarterly payments. Tennant paid $0.295 per share on each ex-dividend date from November 29, 2024, through August 29, 2025. The rate then moved to $0.31 for the four ex-dividend dates from November 28, 2025, through August 31, 2026, before the latest increase to $0.325. Tennant’s dividend history confirms that cadence.
Full-year distributions increased from $0.89 in 2020 to $0.94 in 2021, $1.02 in 2022, $1.08 in 2023, $1.14 in 2024 and $1.20 in 2025. The corresponding annual increases were 5.6%, 8.0%, 5.9%, 5.6% and 5.3%. That record shows relatively consistent mid-single-digit growth, with 2022 the strongest year in the period. The five-year record is summarized as 6.0% annual growth.
Tennant’s own release places the current increase within a 55-year sequence of higher annual cash dividends. The recent payment record supports the broader pattern: increases have been incremental, predictable and implemented through the quarterly rate rather than special distributions.
Is the dividend covered?
The dividend consumes 91% of earnings. That is a high earnings payout ratio because most reported profit is being distributed, leaving less earnings capacity to absorb a downturn or fund other uses of capital without relying on the balance sheet and future cash generation.
SmarterDividends nevertheless rates the dividend A, with a safety score of 86. The grade means very safe within the 80-100 scoring range. It reflects the company’s payment record and broader financial characteristics, while the 91% earnings payout ratio and recent working-capital pressure remain the principal coverage constraints. The grade describes relative safety, not a guarantee that the rate cannot change.
Yield and valuation
The forward yield is 1.80%, compared with the Industrials sector median of 1.60%. The yield is therefore above the sector benchmark, although the difference is modest and the payment remains primarily a record of steady growth rather than a high current-income distribution.
At a share price of $74.01, SmarterDividends’ fair-value estimate is $61.99. The valuation verdict is fair and the stated relationship to fair value is 7% downside. The shares have recorded a 9.1% loss over the past year, but that price movement does not change the declared payment or its December schedule.
What to watch
The immediate calendar item is the November 30, 2026, ex-dividend date. Investors who hold shares before the ex-dividend date are positioned for the December 15, 2026, payment under standard market settlement conventions.
Beyond the payment, the next operating update will be important for evidence that Tennant is improving working-capital efficiency and stabilizing its North American ERP system. The latest filing identified receivables, inventory, supplier performance, material availability and the pace of backlog reduction as concrete variables affecting cash conversion and operational recovery.
Margin quality also warrants attention. The third quarter benefited from a tariff refund, while management continued to cite inflation, parts constraints and production inefficiencies as underlying pressures. Future results will show whether operating cash flow and earnings coverage move into closer alignment with the company’s longstanding dividend policy.
TNC dividend data
From the SmarterDividends dataset, updated daily
- Forward yield
- 1.80%
- Payout ratio
- 91%
- Growth streak
- 38 yrs
- Safety grade
- A · 86/100
| Ex-dividend date | Amount | Change |
|---|---|---|
| Aug 31, 2026 | $0.3100 | +0.0% |
| May 29, 2026 | $0.3100 | +0.0% |
| Feb 27, 2026 | $0.3100 | +0.0% |
| Nov 28, 2025 | $0.3100 | +5.1% |
| Aug 29, 2025 | $0.2950 | +0.0% |
| May 30, 2025 | $0.2950 | +0.0% |
| Feb 28, 2025 | $0.2950 | +0.0% |
| Nov 29, 2024 | $0.2950 | +5.4% |
Full TNC dividend history →·Next ex-dividend date (Nov 30, 2026) →
Frequently asked questions
When is TNC’s next ex-dividend date?
Tennant’s next ex-dividend date is November 30, 2026. The payment date is December 15, 2026.
How much is Tennant’s new quarterly dividend?
The new quarterly dividend is $0.325 per share, up 4.8% from $0.31.
How much is TNC’s dividend per year?
The annual dividend is $1.30 per share. That produces annual income of $130.00 for every 100 shares.
Is Tennant’s dividend safe?
SmarterDividends rates the dividend A with a safety score of 86, meaning very safe within the 80-100 range. The earnings payout ratio is 91%.
What is TNC’s dividend yield?
The forward yield is 1.80%, compared with the Industrials sector median of 1.60%.
Sources
See TNC's full dividend profile
Yield, payout, safety score, history and the next ex-dividend date.
View TNCEvery dividend increases this month, with the data behind it: Dividend Increases, November 2026.
More dividend news
Western Alliance Raises Quarterly Dividend 9.5% to $0.46
Western Alliance’s quarterly payout rises 9.5% to $0.46, with a 19% earnings payout ratio, a B safety grade and payment due November 27, 2026.
Dorian LPG Raises Irregular Dividend 25.0% to $1.25
Dorian LPG lifted its irregular quarterly dividend 25.0% to $1.25, extending capital returns after strong freight rates and vessel sales boosted liquidity.
Sunoco Raises Quarterly Distribution 1.3% to $1.0148
Sunoco lifts its quarterly distribution 1.3% to $1.0148, pairing a 5.91% forward yield with stronger third-quarter distributable cash flow and sound coverage.

Diamondback Energy Raises Dividend 7.3% to $1.18
Diamondback lifts its quarterly base dividend to $1.18 as cash flow, debt reduction and stronger production guidance support the higher payout.
Enerflex Raises Quarterly Dividend 93.6% to $0.06
Enerflex raises its quarterly dividend 93.6% to $0.06 as stronger cash generation, lower leverage and record backlog support shareholder returns.